 Trang Chủ


In Vietnam, the 2012 Law on DI laid the foundation for a relatively comprehensive legal framework for DI operations. However, in tandem with the rapid development of the financial market, the process of restructuring the credit institution system, the requirements for resolving weak credit institutions, the increasing risk of bank runs, and the demand for digital transformation in banking operations, the 2012 Law gradually revealed certain limitations. Against this backdrop, the National Assembly's enactment of the 2025 Law on DI, effective from May 1, 2026, replacing the 2012 Law on DI, represents a significant institutional advancement, both in terms of protecting depositors and ensuring systemic safety.
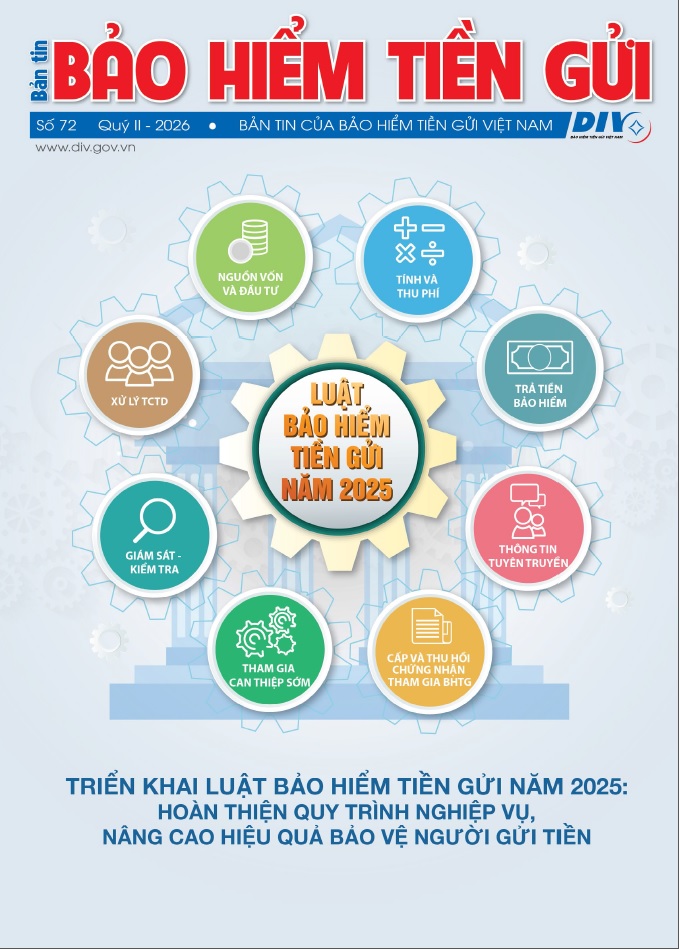
Notably, the 2025 Law has significantly restructured a number of core policy groups, spanning from insurable deposits, the DI premium mechanism, the triggers for DI payout, the coverage limit, payout procedures, to the duties, powers, and intervention tools of the deposit insurer. Therefore, studying the 2025 Law on DI requires an approach not only at the level of normative description but also at the depth of the legislative thinking, policy orientation, and the systemic risk management model that the Law embodies.
The Fundamental New Features of the 2025 Law on DI
Repositioning the Role of DI within the National Financial Safety Net
Compared with the 2012 Law on DI, the 2025 Law continues to affirm the goal of protecting the legitimate rights and interests of depositors, while placing greater emphasis on DI’s role in contributing to the stability of the credit institution system and ensuring the safe and sound development of banking activities. Under the 2012 Law, Article 3 stipulated that DI aims to "protect the legitimate rights and interests of depositors, contribute to maintaining the stability of the credit institution system, and ensure the safe and sound development of banking activities." Article 3 of the 2025 Law carries forward this underlying principle, but places it within a broader policy framework, linked to more clearly defined intervention tools available to the deposit insurer.
In parallel, the 2025 Law continues to affirm that the deposit insurance organization is a state-owned financial institution operating on a non-profit basis, while granting it more public powers and risk management tools. Therefore, the legal nature of the DI organization is thereby more clearly reinforced as a public institution serving the national financial safety policy.
Refining Provisions on Insurable and Uninsurable Deposits
Regarding insurable deposits, the 2025 Law maintains the core principle of insuring only individual deposits in Vietnamese dong, while articulating this principle in a more comprehensive and updated manner, and explicitly aligning it with the forms of deposits prescribed under the Law on credit institutions. At the same time, the 2025 Law introduces several new exclusions, such as deposits held by shareholders owning more than 5% of the charter capital of the credit institution itself, deposits held by persons related to such shareholders in cases prescribed by the Law on credit institutions, as well as compulsory savings deposits at microfinance institutions. Compared with the 2012 Law, these exclusions show that DI policy has been clarified to exclude from protection those parties that have a special interest relationship or that must bear higher responsibility for the risks of the depository institution.
Reforming the DI Premium Mechanism
Under the 2012 Law, the Prime Minister was vested with the authority to issue a DI premium frame upon the proposal of the State Bank of Vietnam (SBV). Based on this frame, the SBV determined a specific premium rate applicable to each insured institution, drawing on the results of the assessment and classification of these institutions. While this model ensures a degree of control, it also constrains the premium mechanism's flexibility to a certain extent.
The 2025 Law introduces a significant change by entrusting the SBV’s Governor with the authority to determine premium rates and to apply either a flat-rate premium or a differential premium system appropriate to the specific characteristics of Vietnam's credit institution system in each period. Compared with the previous model, this represents a more pronounced step toward decentralization and specialization. A particularly important new point is that the 2025 Law also provides that a credit institution placed under special control shall be exempted from paying deposit insurance premiums and allowed to temporarily defer payment of any underpaid or overdue premiums and previously accrued late-payment amounts, but must have a repayment schedule incorporated into the restructuring plan. This mechanism reflects a new regulatory mindset: in resolving a weak credit institution, the goal of preserving its recoverability and safeguarding systemic stability is prioritized over the immediate requirement to collect full premiums.
At the same time, the mechanism for addressing premium payment violations has also been adjusted. Whereas the 2012 Law allowed, in certain cases, the deposit insurer to submit a written request for the SBV to debit the account held by an insured institution at a bank in order to collect outstanding premiums and fines, the 2025 Law shifts to a mechanism whereby the deposit insurance organization requests the SBV to handle the matter in accordance with applicable law. This adjustment is consistent with the correct position of a specialized state management agency.
Significantly Expanding the Duties and Powers of the DI Organization
This is one of the most fundamental changes in the 2025 Law. Under the 2012 Law, the duties and powers of the DI organization centered primarily on issuing deposit insurance certificates, collecting premiums, managing financial resources, reimbursing depositors, examining compliance with the Law on DI, participating in special control under the direction of the SBV, and participating in asset management and liquidation.
The 2025 Law substantially expands these powers. Pursuant to Article 14, the DI organization shall not only continue to perform its existing functions but also be empowered to: examine insured institutions according to plans and scopes assigned by the SBV; synthesize, analyze, and process information with a view to detect and recommend the SBV timely handle law violations and risks causing unsafety in the credit institution system; participate in the processes of early intervention, special control, and credit institution resolution; contribute to the formulation of bankruptcy plans; and engage in the management and liquidation of assets of insured institutions.
This expansion demonstrates that the deposit insurance organization has shifted from the position of a "payer of insurance obligations" to a "participant in systemic safety management". This represents not merely a change in legislative technique, but an adjustment to the institutional model itself.
Redesigning the Triggering Mechanism for Payout Obligations and Reimbursement Procedures
The 2012 Law provided that the obligation to make DI payouts shall arise primarily when the SBV issues a document terminating special control, or terminating or refraining from applying measures to restore insolvency, yet the credit institution remains insolvent, or when the SBV issues a document determining that a foreign bank branch has become unable to meet its deposit payment obligations. While this approach is safe, it is relatively slow and largely dependent on the broader credit institution resolution process.
The 2025 Law introduces two crucial new points. First, the cases triggering the insurance payout obligation have been expanded to include the situation where the SBV suspends the deposit-taking activities of a credit institution placed under special control and that institution has accumulated losses exceeding a certain threshold according to its latest audited financial statements. Second, in cases where it is necessary to safeguard systemic stability and to preserve social order and safety, the SBV may decide to initiate DI payout pursuant to Clause 2, Article 36 of the 2025 Law. This represents a highly significant shift, as it enables deposit insurance policy to function as an early response tool rather than merely a tool for dealing with consequences.
With respect to procedures, the 2012 Law stipulated that, within 10 working days from the triggering event, the insured institution must submit a DI payout application dossier; the maximum period for commencing DI payout is 60 days. The 2025 Law markedly shortens these: the dossier must now be submitted within 5 working days, and the maximum period for commencing DI payout reduced to 45 days. This acceleration carries particular weight in a context where the psychology driving bank runs can spread rapidly. Reimbursement speed thereby becomes a determinant of systemic stability, rather than a mere administrative indicator.
Introducing Flexibility into the DI Coverage Limit Setting Mechanism
The 2012 Law provided that the Prime Minister shall set the DI coverage limit upon the SBV’s proposal in each period. The 2025 Law transfers this authority to the SBV’s Governor, notably, introduces an exception mechanism: in circumstances where it is necessary to safeguard systemic stability and preserve social order and safety, the Governor may set a coverage limit exceeding the standard one, up to a maximum that cover all insurable deposits held by depositors at the insured institution.
This amendment indicates that the lawmakers have embraced a more flexible approach to policy instruments in emergency situations. The coverage limit, therefore, is no longer just a rigid, long-term stable cap but becomes a tool that can be adjusted in response to evolving systemic risk conditions.
Adding a Separate Chapter on Participation in Credit Institution Resolution and Crisis Management
The most striking difference between the two Laws is that the 2025 Law introduces an entirely new Chapter VII on participation in the resolution of credit institutions subject to early intervention and special control, as well as participation in the handling of incidents and crises in the operations of credit institutions. This subject matter was wholly absent from the 2012 Law.
Under this chapter, the deposit insurer is allowed, in certain circumstances, to provide special loans from its operational reserve fund, with special loan amounts being given priority in repayment; to participate in safeguarding systemic stability and preserving social order and safety; to obtain special loans from the SBV at a zero-percent interest rate and without collateral in cases where the operational reserve fund is insufficient to make DI payouts; and to engage in handling incident and crises pursuant to decisions of the Government. These provisions demonstrate that DI in Vietnam has shifted away from a model predominantly oriented toward traditional payout toward one that incorporates substantial elements of a systemic risk minimizer.
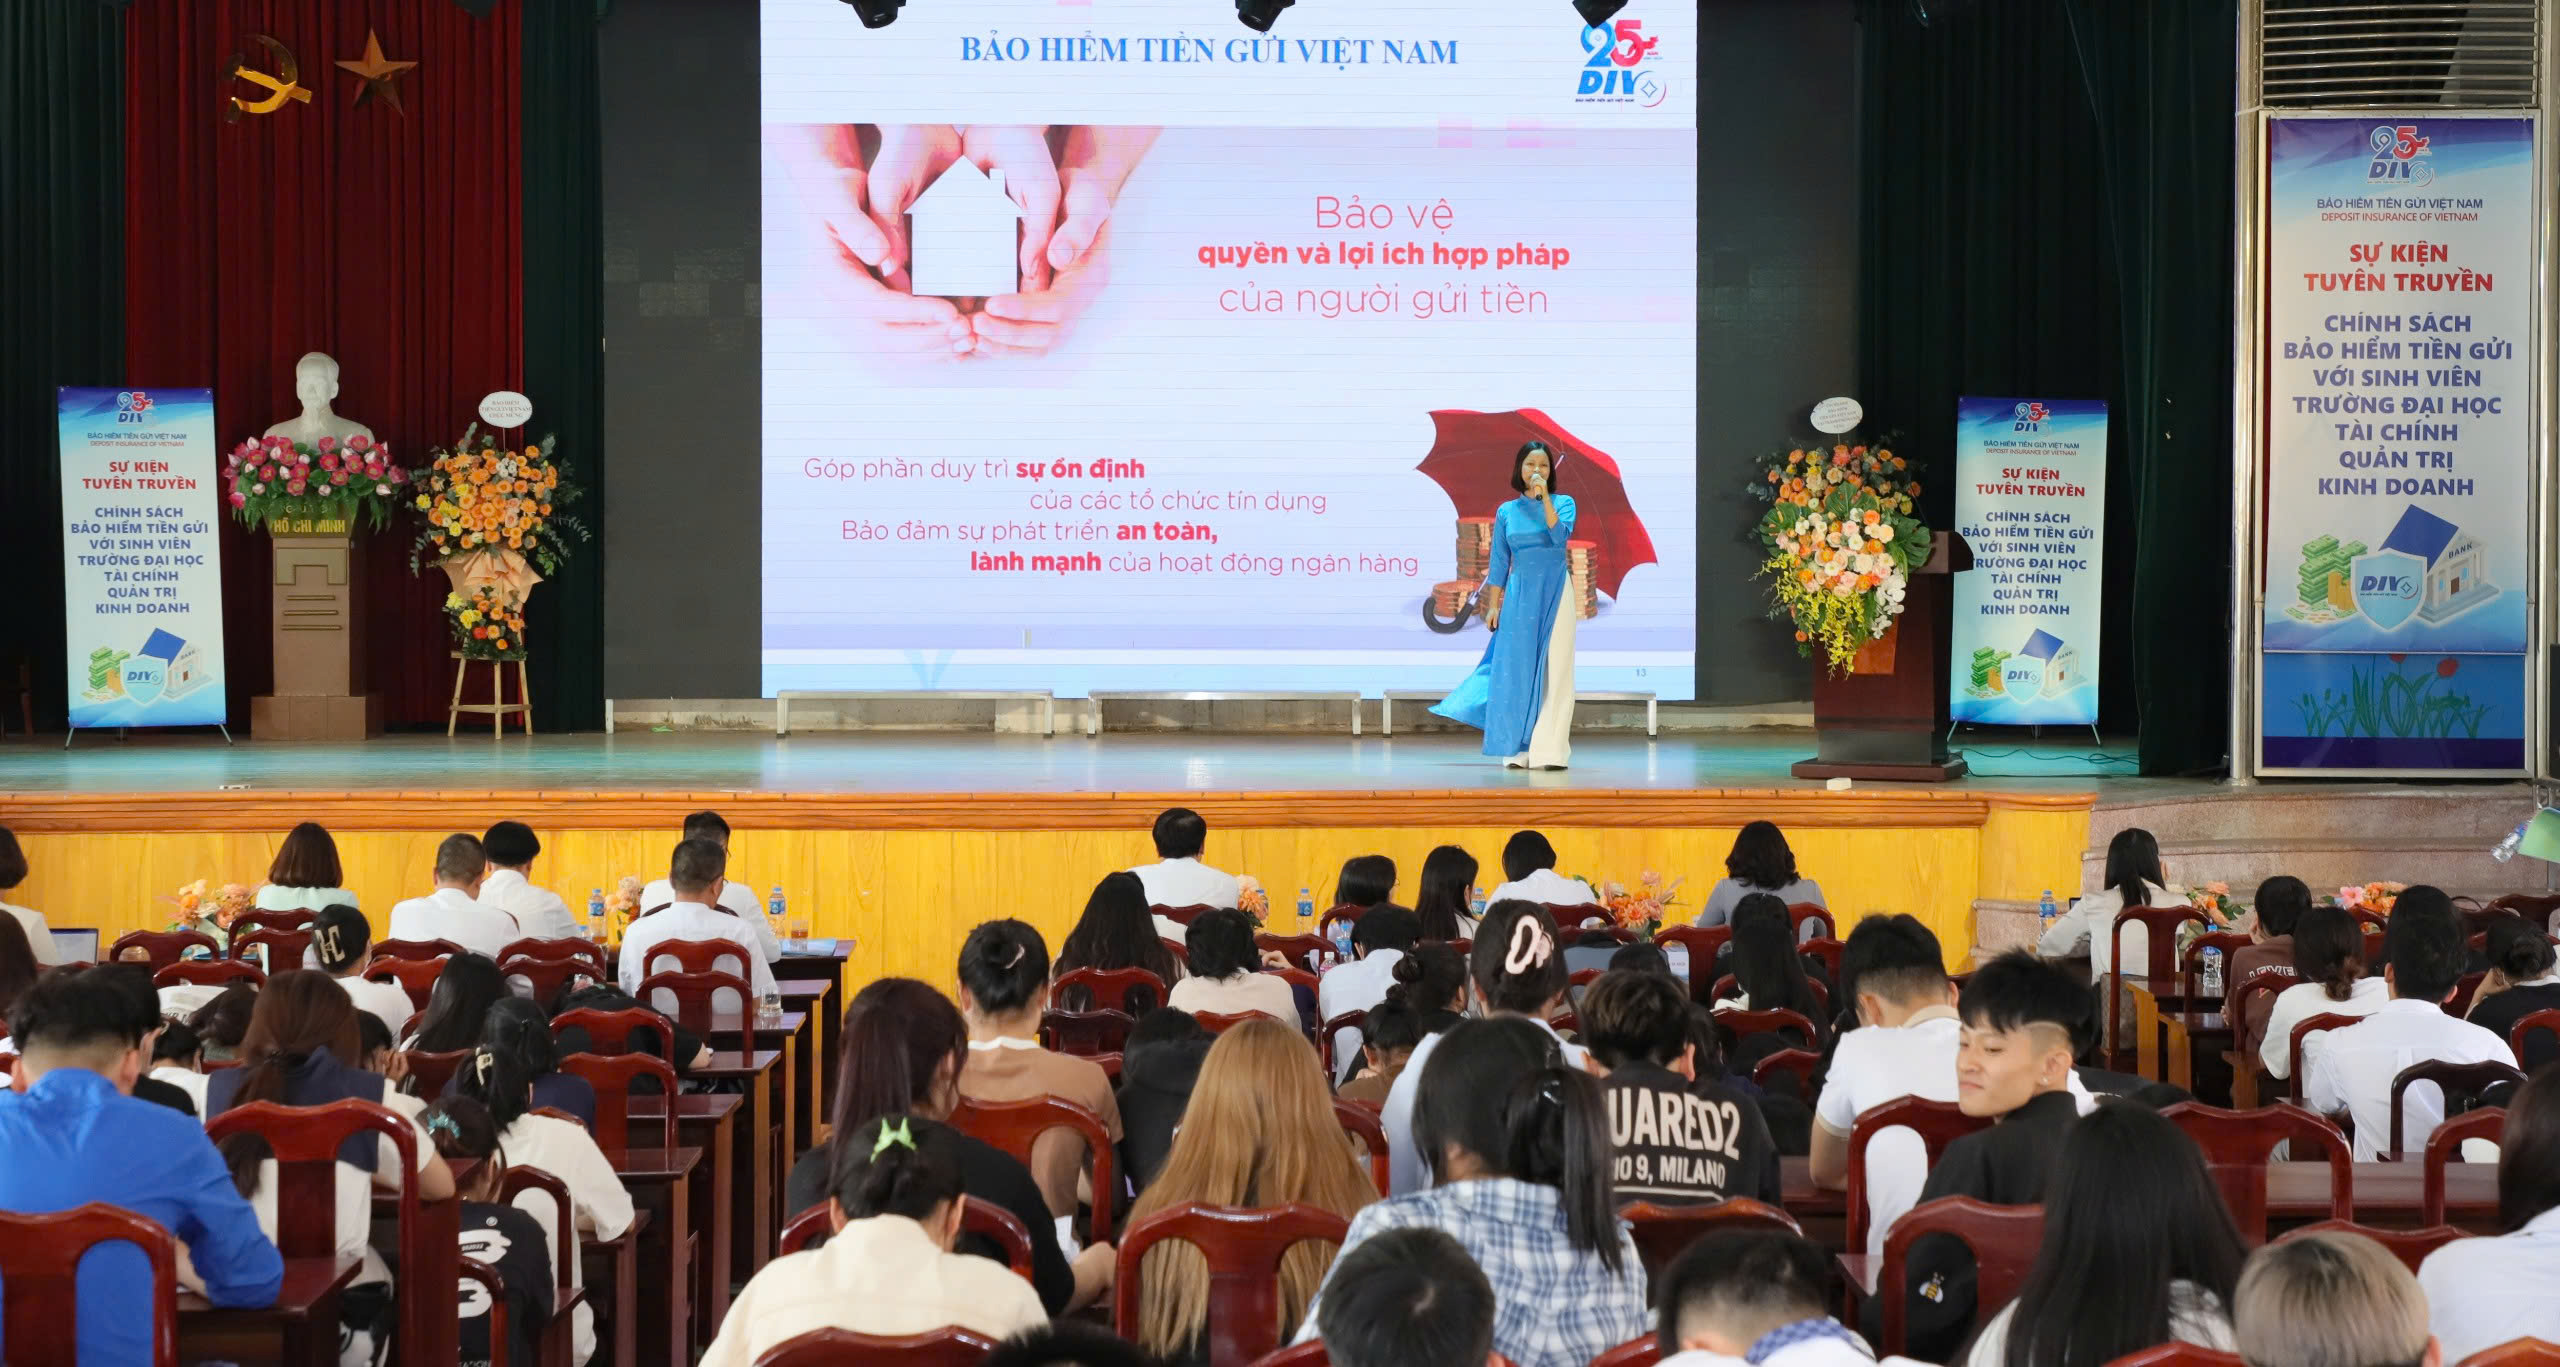
Raising public awareness to bring deposit insurance policy to life
Comparison of the 2012 Law and the 2025 Law by Policy Group
Policy Group on the Mandate and Legal Status of DI
The 2012 Law defined the purpose of DI as protecting the legitimate rights and interests of depositors, contributing to the stability of the credit institution system, and ensuring the safe and sound development of banking activities. The 2025 Law inherits this sprit but further articulates the role of DI in maintaining systemic stability, while substantially expanding its legal instruments to realize the above purpose. Thus, from a policy standpoint, the 2025 Law does not alter the fundamental goal but rather elevates it from a declarative statement to an institutional design.
Policy Group on Insurable Deposits
Both the 2012 and 2025 Laws maintain the principle of insuring only individual deposits in Vietnamese dong. However, the 2025 Law sets out more rigorous and detailed provisions regarding uninsurable cases, broadening the scope of exclusions to encompass major shareholders, related persons, and compulsory savings deposits at microfinance institutions. This reflects a redesigned protection policy that more precisely targets the parties genuinely warranting protection, avoiding the extension of DI to those with the capability to control or influence the risks of the deposit-taking institution itself.
Policy Group on DI Premiums
The 2012 Law established a premium assessment model based on a frame determined by the Prime Minister. The 2025 Law directly assigns the SBV Governor to set premium rates and to apply either a flat-rate premium or a differential premium system. From a policy perspective, this represents a shift from a multi-tiered, relatively rigid management model to a more flexible one, closer to substantive risk management. At the same time, the 2025 Law introduces mechanisms for premium exemption, deferral, and the handling of overdue payments in the context of special control, demonstrating that the DI premium mechanism has been situated within an organic relationship with the policy framework for restructuring weak credit institutions.
Policy Group on Powers of the DI Organization
This group represents the most significant change. The 2012 Law conferred upon the DI organization a set of administrative and operational powers, along with limited involvement in special control. The 2025 Law substantially expands these powers to include conducting examinations in accordance with plans assigned by the SBV, analyzing and processing information, detecting risks and recommending risk management, participating in early intervention, formulating bankruptcy plans, and participating in asset management and liquidation. From a policy standpoint, the 2025 Law has transformed the DI organization from a payout entity into one that plays a substantive role in systemic risk management.
Policy Group on DI Payout
The 2012 Law adopted a relatively cautious approach with the triggers for payout closely tied to the credit institution resolution process. Payout procedures were comparatively lengthy, and the coverage limit was less flexible. The 2025 Law comprehensively changes this policy group by expanding the triggers, shortening the timeframe for dossier preparation and payout, and simultaneously allowing the flexible application of the coverage limit in special situations. Payout policy has thereby shifted from a model centered on procedural compliance to one centered on timely reimbursement aimed at stabilizing the system.
Policy Group on Weak Credit Institution Resolution and Crisis Management
The 2012 Law hardly established a dedicated framework for the DI organization’s role in crisis management. The 2025 Law addresses this gap by introducing a separate chapter on special loans, participation in safeguarding systemic stability, prioritized repayment of special loans, special borrowing from the SBV, and participation in incident and crisis management. This is a pivotal shift, bringing Vietnam's DI law closer to the modern model of an active component within the financial safety net.
The Legislative Value and Practical Significance of the 2025 Law on DI
Laying a More Comprehensive and Coherent Legal Foundation for DI
From a legislative standpoint, the value of the 2025 Law lies first and foremost in establishing a more complete, up-to-date framework that is coherently interconnected with the Law on credit institutions. Its new provisions do not detach DI from the broader context of systemic safety management. Rather, they situate it precisely at the center of the interconnected relationship among depositor protection, market discipline, credit institution restructuring, and crisis management.
Substantively Strengthening Depositor Protection
The 2025 Law protects depositors not only by preserving the institutional mechanism for DI payout but also by broadening the conditions for earlier reimbursement, shortening the payout timeframe, and enhancing the deposit insurance organization's capacity to intervene before risks escalate beyond control. This constitutes a substantively stronger form of protection than an approach that only triggers reimbursement after a failure has fully unfolded.
Enhancing the Capacity to Respond to Systemic Risks
The most prominent feature of the 2025 Law is the increased capacity to respond to systemic risks. The provisions on special loans, special borrowing from the SBV, the management of bank runs, the flexible coverage limit mechanism, and participation in incident and crisis management demonstrate that DI has been codified into law as a crisis management tool, rather than merely an insurance mechanism in the narrow sense.
Establishing a Legal Foundation for Data Management and Digital Transformation
The expansion of the DI organization's right to access, synthesize, analyze, and process information under the 2025 Law carries considerable significance for digital transformation. In the era of digital banking, a modern DI system cannot exist without timely, accurate, and interconnected data. The 2025 Law essentially lays an initial legal foundation for building a data-driven and rapid-response DI model.
Several Considerations for Law Implementation
First, it is necessary to promptly issue comprehensive guiding documents, particularly with respect to premium rates, a methodology for applying flat-rate or differential premiums, procedures for special lending, a mechanism for accessing customer data, and criteria for applying a special DI coverage limit.
Second, it is essential to ensure synchronous coordination among the DI organization, the SBV, credit institutions, and other relevant entities in data provision, examination, risk warning, and emergency response. In the absence of an operational coordination mechanism, many progressive provisions of the Law will struggle to exert their effect in practice.
Third, the financial capacity, data analysis and operational capabilities of the DI organization should be further strengthened. While the Law has expanded the organization's functions, the extent to which these can be carried out in practice will depend on its organizational conditions and resources available for implementation.
Fourth, public awareness about the Law on DI should be promoted, so that depositors and the public gain a clear understanding of the scope of protection, the coverage limit, the procedures for exercising their rights, and the nature of this policy. In many cases, the effectiveness of systemic stabilization derives not solely from the Law’s content, but also from the degree to which the public trusts and correctly understands it.
The 2025 Law on Deposit Insurance marks a significant step forward for Vietnam's financial and banking law in this new phase. Whereas the 2012 Law primarily laid the groundwork for forming a DI mechanism, the 2025 Law has elevated that mechanism to a new stage of development — more modern, proactive, and more tightly integrated with the requirement to ensure the safety of the credit institution system.
The defining feature of the 2025 Law is the transformation of the DI legal model: from an institution oriented toward payout to one capable of participating in the prevention, mitigation, and resolution of systemic risks. In this sense, it can be affirmed that the 2025 Law on DI truly serves as the legal foundation for DI operations in a new era.
Department of Research and International Cooperation (Translation)