 Trang Chủ


People’s credit funds (PCFs) play an important role in poverty reduction, curbing loan sharking in rural areas, and expanding access to formal financial services, particularly for people in remote and disadvantaged communities. Given their grassroots presence and close connection with local communities, the deposit insurance policy - especially the comprehensively amended 2025 Law on Deposit Insurance, which took effect on May 1, 2026 - is expected to have a positive impact on the PCF system and on the confidence of millions of members and depositors.
On this occasion, the reporter spoke with Mr. Nguyen Duc Dung, Secretary General of the Vietnam Association of People’s Credit Funds (VAPCF).
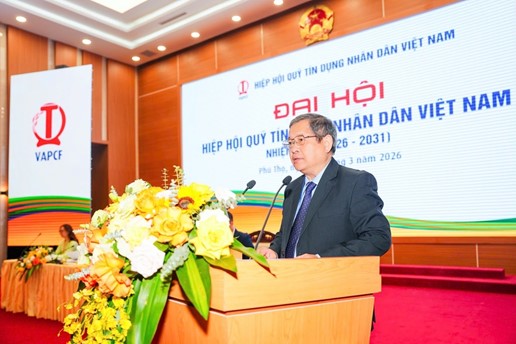
Reporter: From the perspective of the PCF system, how do you assess the significance of the 2025 Law on Deposit Insurance?
Mr. Nguyen Duc Dung: Compared with the 2012 Law on Deposit Insurance, the 2025 Law introduces a number of important amendments and supplements aimed at strengthening the protection of depositors’ legitimate rights and interests, contributing to the safety of the credit institution system, and promoting the stable and sound development of banking operations. For the PCF system, these implications are particularly clear and direct.
Vietnam currently has 1,172 PCFs operating nationwide. They have contributed to the effective implementation of the National Financial Inclusion Strategy by expanding access to formal financial services, especially in rural areas. They also help curb usury, support household economic development, and promote the rural economy. Depositing members of PCFs are mainly farmers, workers and laborers - groups with modest savings, limited access to financial information, and relatively high sensitivity to market fluctuations.
Against this backdrop, a comprehensive, transparent and robust legal framework for depositor protection is essential. For many members, deposits placed at PCFs are not merely financial assets; they represent the result of long-term savings and constitute an important financial resource for their families. Therefore, the 2025 Law on Deposit Insurance not only protects depositors’ interests, but also reinforces members’ confidence in the PCF system. This, in turn, helps stabilize mobilized funds, improve credit supply capacity, and promote socio-economic development at the grassroots level.
Reporter: Which new provisions of the 2025 Law on Deposit Insurance do you consider to have the most direct impact on the PCF system?
Mr. Nguyen Duc Dung: VAPCF and its members welcome the issuance of the 2025 Law on Deposit Insurance and its guiding documents, which contain a number of relevant and practical new provisions.
First, one of the most direct and significant changes for the PCF system is the broader determination of the circumstances triggering the deposit insurance payout obligation, enabling depositors to receive insured payouts earlier. From May 1, 2026, the deposit insurance payout obligation may arise in one of three cases:
(i) the bankruptcy plan of a credit institution is approved, or the State Bank of Vietnam (SBV) issues a written determination that a foreign bank branch is unable to repay deposits to depositors;
(ii) the SBV issues a written decision suspending the deposit-taking activities of a specially controlled credit institution, and that institution has accumulated losses exceeding 100% of its charter capital and reserve funds according to its latest audited financial statements; or
(iii) the SBV issues a written notice to the deposit insurer on insurance payout in accordance with Clause 2, Article 36 of the 2025 Law on Deposit Insurance.
For the PCF system, this provision is particularly important. Previously, deposit insurance reimbursement was often linked to a prolonged resolution process, resulting in long waiting periods and directly affecting depositors’ interests and sentiment. As PCF members are mostly people with modest savings and high sensitivity to risk, any delay may undermine confidence and lead to undesirable consequences. The new mechanism can significantly shorten the payout timeline, thereby promptly protecting depositors’ legitimate rights and interests while limiting psychological instability and possible contagion effects within local communities.
Second, the application of a deposit insurance premium rate of 0.1% per year, calculated on the average balance of insured deposits at insured institutions, provides meaningful support for the PCF system. This rate is lower than the 0.15% per year applied to other credit institutions. A notable feature is that, in addition to their obligation to participate in deposit insurance under the Law on Deposit Insurance, PCFs must also contribute to the System Safety Fund under Article 25 of Circular No.27/2024/TT-NHNN, with an annual contribution equal to 0.05% of the average outstanding loans of the preceding year ending on December 31 of the Cooperative bank and PCFs.
Together with the State’s deposit insurance policy, the PCF System Safety Fund creates a “two-layer” protection mechanism for the PCF system and depositors. While deposit insurance protects depositors when a credit institution becomes insolvent or goes bankrupt, the System Safety Fund provides early internal support to prevent failures, restore operations, and maintain the stability of the PCF system. This shows that the PCF system is not only protected by the State, but also proactively contributes resources to safeguard itself based on the principles of linkage, cooperation and mutual support.
Accordingly, setting a separate and lower deposit insurance premium rate for PCFs - 0.1% instead of 0.15% - is appropriate to the organizational characteristics and operational realities of the PCF system. This policy helps reduce financial costs, enabling PCFs to concentrate resources on serving members and developing safely and sustainably. It also reflects the State management authority’s recognition of the cooperative nature, community linkage and mutual support mechanism of the PCF system. At the same time, the lower rate encourages PCFs to improve governance capacity, strengthen self-protection, and contribute to system safety and stability through the PCF System Safety Fund.
Third, according to the information available to me, the SBV is developing a draft Circular on the deposit insurance coverage limit. Hence, the maximum reimbursement by the deposit insurer for all insured deposits, including principal and interest, of one depositor at one insured institution when the payout obligation arises is expected to be raised to VND 350 million, approximately 2.8 times the current limit of VND 125 million.
This is a reasonable adjustment that would gradually bring Vietnam closer to international practices. A coverage limit equivalent to around 2.8 times GDP per capita is particularly meaningful as both the scale of deposits and household savings continue to increase. With a coverage limit of VND 350 million, around 80% of depositors at PCFs are expected to have their deposits fully insured. Fully insured deposits would account for approximately 37% of the total deposit balance in the PCF system when the deposit insurance payout obligation arises.
This indicates that the new coverage limit, if issued, would largely protect the majority of depositors at PCFs, particularly people in rural, remote and disadvantaged areas, where most depositors have modest savings but a strong need for safety and assurance for their accumulated funds. The policy would also help further strengthen members’ and depositors’ confidence in the PCF system.
Reporter: What should be done to ensure that the 2025 Law on Deposit Insurance effectively supports the development of the PCF system?
Mr. Nguyen Duc Dung: To ensure that the 2025 Law on Deposit Insurance is effectively implemented in practice, it is first necessary to strengthen communication and policy dissemination so that the public, PCF members and local communities properly and fully understand the deposit insurance policy and the new provisions of the Law. At the same time, the PCF system’s awareness and implementation capacity must be enhanced to ensure consistent, uniform and compliant implementation across the system.
DIV should therefore continue to promote broad-based public communication. It should also organize training programs, workshops and in-depth seminars on the 2025 Law on Deposit Insurance and its guiding documents, especially SBV’s regulations on deposit insurance premium, coverage limit, examination procedures for insured institutions, and other tasks assigned by the SBV.
VAPCF is ready to coordinate with DIV and the Coop-Bank to organize training programs by local clusters, in line with the operational characteristics of PCFs. These programs would help PCF staff better understand legal regulations, improve their professional skills, and implement the policy consistently across the system. We will also strengthen its engagement with members, collect feedback on practical difficulties, and promptly make recommendations to competent State management agencies to address issues arising during implementation.
In addition to communication and training, the coordination mechanism among the SBV, DIV, the VAPCF should be further strengthened, particularly in supporting PCFs, preventing risks and addressing emerging difficulties. Close coordination will not only improve the operational capacity and self-protection capability of the PCF system, but also better protect depositors’ legitimate rights and interests. This will further consolidate public and member confidence in the PCF model — a cooperative financial institution with strong community-based characteristics in rural areas.
Reporter: What message would you like to convey to member PCFs and people depositing money at PCFs now that the 2025 Law on Deposit Insurance has taken effect?
Mr. Nguyen Duc Dung: Protecting depositors’ interests is not solely the responsibility of DIV. It is also the responsibility of credit institutions, including PCFs, through safe and effective operations, strict compliance with legal regulations, and the prioritization of members’ and customers’ interests. In the new development context, the PCF system should focus on improving governance and management capacity, strengthening risk control, applying technology, and standardizing operations toward greater professionalism, safety and sustainability.
With the new provisions of the 2025 Law on Deposit Insurance, many depositors at credit institutions, including PCFs, will have their deposits fully insured. I hope depositors will continue to place their trust in and accompany PCFs. Each deposit placed at a PCF is not only a safe savings asset for a family, but also a valuable source of capital that supports local people in borrowing for production and business, creating jobs, improving income, and building stronger communities. This is also the humanistic value and distinctive mutual-support spirit of the PCF model that should continue to be preserved and promoted in the new period.
Reporter: Thank you very much.
Top of Form
Bottom of Form
Communication Department